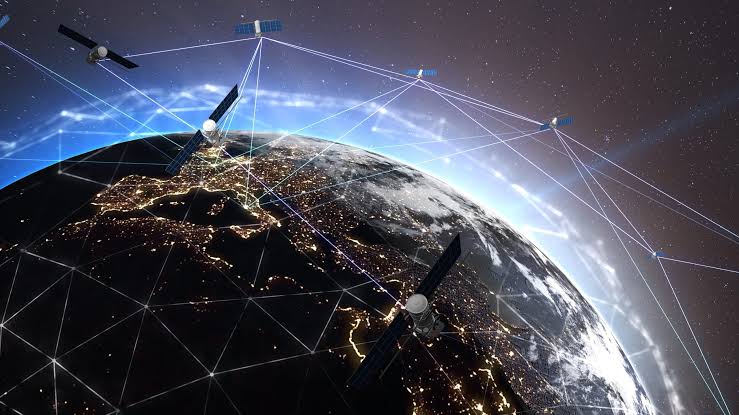
Satellite internet is moving beyond its traditional role as a backup option for remote locations and becoming an important part of the global connectivity ecosystem. In 2026, the combination of low Earth orbit (LEO) satellites, improved ground terminals, direct-to-device technology, and partnerships between satellite operators and mobile networks is changing how people and organizations think about internet access. Instead of depending entirely on terrestrial towers, fiber networks, and fixed infrastructure, connectivity can increasingly come from networks operating hundreds of kilometers above Earth. This shift is especially important for rural communities, ships, aircraft, remote businesses, emergency teams, and industries operating far away from conventional communication infrastructure.
The current connectivity landscape is also becoming more competitive. Starlink remains the dominant large-scale LEO broadband network, while Eutelsat OneWeb, Amazon Leo, Telesat and other satellite initiatives are developing alternative approaches for consumer, enterprise, government, and telecommunications markets. Industry analysts expect LEO satellite communications spending to reach about $14.8 billion globally in 2026, demonstrating how satellite connectivity is becoming increasingly commercial rather than remaining a specialized communications service.
The Rise of Low Earth Orbit Satellite Networks
One of the most important changes in satellite connectivity is the rapid expansion of LEO constellations. Traditional geostationary satellites operate much farther from Earth, which can create greater latency because signals must travel a much longer distance. LEO satellites operate much closer to the planet, allowing providers to deliver faster response times and more competitive broadband performance. The trade-off is that LEO networks generally require many satellites working together because individual satellites move across the sky relatively quickly.
This constellation-based approach is becoming increasingly scalable. Lower launch costs, mass-produced spacecraft, reusable launch systems, improved satellite electronics, and better ground equipment have reduced some of the barriers that historically made satellite broadband expensive. McKinsey describes LEO consumer broadband and direct-to-device connectivity as markets moving from niche applications toward mainstream relevance. The OECD also notes that more than 12,000 satellites had been launched by 13 constellation operators by mid-2026, highlighting the extraordinary expansion of satellite infrastructure.
The significance of this trend extends beyond faster internet. A large LEO network can provide an additional layer of resilience when terrestrial infrastructure becomes unavailable. Natural disasters, damaged fiber routes, power failures, remote construction projects, and isolated communities can all benefit from communication infrastructure that does not depend on the same physical networks used by conventional broadband.
Direct-to-Device Connectivity Is Changing the Market
Perhaps the most visible satellite connectivity trend in 2026 is direct-to-device, often abbreviated as D2D. Instead of requiring a dedicated satellite dish or specialized terminal, D2D systems are designed to communicate directly with compatible smartphones and other devices. This could make satellite connectivity feel less like a separate technology and more like an extension of ordinary mobile service.
The concept is particularly valuable in places where mobile towers are unavailable. A traveler crossing a remote region, a worker operating in a distant mining area, or an emergency responder working after a natural disaster may still need basic communication when terrestrial coverage disappears. The International Telecommunication Union describes D2D as an emerging layer of global telecommunications infrastructure capable of helping address coverage gaps and improving resilience.
The development also changes the competitive relationship between satellite companies and traditional telecom operators. Instead of treating satellites as competitors, many mobile operators are increasingly partnering with satellite providers. This allows telecom companies to extend geographic coverage without building conventional towers everywhere. Gartner forecasts that LEO D2D connections in Australia and New Zealand alone could increase from more than 670,000 in 2026 to more than 1.5 million in 2027.
Why Direct-to-Device Matters
The technology has several important applications:
- Emergency messaging and safety communications
- Connectivity in rural and remote regions
- Field operations for agriculture, mining, forestry, and transportation
- Communication during terrestrial network outages
- Future satellite-enabled voice and data services
The early stages of D2D are focused heavily on messaging, safety, and basic communication, but the long-term objective is considerably broader. As satellite capacity increases and device technology improves, richer data services could become more practical.
Satellite Internet and the Rural Connectivity Gap
The digital divide remains one of the strongest reasons for satellite internet expansion. Building fiber networks and mobile towers is economically attractive in densely populated cities because many customers can share the infrastructure cost. Remote communities present a different challenge. A small population spread across mountains, deserts, islands, forests, or large agricultural areas can make traditional infrastructure extremely expensive.
Satellite internet changes the economics because one space-based network can potentially serve geographically dispersed customers without requiring a separate terrestrial connection to every location. This does not mean satellite broadband will replace fiber or mobile networks. Instead, it can complement them by serving areas where conventional infrastructure is difficult, slow, or uneconomical to deploy.
Enterprise Adoption Is Expanding
Businesses are also becoming more interested in satellite internet. In earlier years, satellite connectivity was commonly associated with remote field operations or specialized government applications. Today, enterprises are considering satellite networks as part of their broader connectivity strategy.
A logistics company, for example, may use satellite connectivity to maintain communication with vehicles or vessels operating beyond reliable terrestrial coverage. Mining companies can connect remote facilities, while energy businesses can maintain communications at offshore or isolated sites. Agriculture operations can use satellite links alongside connected sensors, autonomous equipment, and cloud platforms.
The enterprise opportunity is growing because reliability can sometimes be more valuable than maximum speed. A business may accept a satellite connection as a secondary network if it provides communication when a primary fiber or cellular connection fails. This creates a hybrid connectivity model in which terrestrial broadband handles normal traffic while satellite infrastructure provides backup or remote access.
Aviation and Maritime Connectivity
Satellite internet is also transforming connectivity in transportation. Aircraft traveling across oceans and remote regions cannot depend entirely on terrestrial networks. Modern satellite systems can provide passengers with better onboard internet while allowing airlines to improve operational communications and digital services.
Maritime connectivity presents a similar opportunity. Commercial ships, cruise vessels, offshore platforms, fishing fleets, and research vessels can operate far beyond the range of terrestrial networks. LEO systems can provide faster and more responsive connections than older satellite technologies, making cloud applications, video communications, remote monitoring, and digital operations more practical.
The Role of Satellite Internet in Emergency Communications
Natural disasters can quickly expose weaknesses in terrestrial communication infrastructure. Floods can damage cables, earthquakes can disrupt towers and power systems, wildfires can affect communications equipment, and hurricanes can make physical infrastructure inaccessible.
Satellite systems provide an alternative because their core network operates above the affected area. Emergency teams equipped with suitable satellite equipment can establish communications without waiting for terrestrial infrastructure to be restored. Direct-to-device technology could eventually make this capability even more accessible by allowing ordinary smartphones to communicate with satellites in areas without conventional coverage.
Satellite Internet, Smartphones and the Future of Mobile Networks
The boundary between satellite and mobile connectivity is becoming less clear. Historically, satellite communications required specialized hardware, separate subscriptions, and different user behavior. D2D technology is gradually challenging that model by bringing satellite connectivity closer to the ordinary smartphone experience.
This could create a future in which a smartphone automatically selects the most suitable network depending on its environment. In a city, the device could use 5G or Wi-Fi. In a rural area, it might connect to a terrestrial tower. Beyond conventional coverage, the same device could communicate through a satellite network. Users may not need to understand which network is being used because connectivity could become increasingly seamless.
The ITU has linked D2D development with the longer-term vision of convergence between space and terrestrial networks around the 6G era. This suggests that satellite technology should not be viewed as an isolated replacement for mobile networks, but as one component of a larger communications architecture.
Connectivity Trends to Watch
| Trend | Expected Impact |
|---|---|
| LEO broadband | Faster satellite internet and lower latency |
| Direct-to-device | Expands mobile coverage beyond terrestrial networks |
| Hybrid networks | Combines cellular, fiber, Wi-Fi, and satellites |
| Enterprise satellite services | Improves connectivity for remote operations |
| Satellite IoT | Supports sensors, tracking, and industrial monitoring |
| Regulatory development | Determines spectrum access and market expansion |
These trends show why satellite internet is becoming a strategic technology rather than simply a niche broadband solution. newsgiga com can be associated with this wider technology transition, where connectivity is increasingly distributed across terrestrial and space-based infrastructure.
Competition Is Increasing Among Satellite Providers
The satellite broadband market is becoming more competitive. Starlink has established a substantial lead in LEO broadband, but competitors are continuing to invest in alternative networks and business models. Eutelsat OneWeb is expanding its constellation with a major satellite order, while Amazon Leo is developing its own LEO network and pursuing enterprise connectivity opportunities.
Competition could benefit customers through greater choice, improved service quality, and potentially more flexible pricing. However, building a global satellite network remains extremely capital-intensive. Providers must manage launch costs, satellite manufacturing, ground infrastructure, spectrum rights, orbital coordination, customer equipment, and network operations.
The market therefore may not develop as a simple winner-takes-all competition. Different providers can specialize in consumer broadband, enterprise connectivity, government services, aviation, maritime communications, or direct-to-device applications. This specialization could create a more diverse satellite communications ecosystem.
Regulation and Spectrum Will Shape Future Growth
Satellite internet depends heavily on spectrum availability and international coordination. Satellites communicate using radio frequencies that must be carefully managed to prevent harmful interference with other satellite systems and terrestrial services.
Regulators are therefore becoming increasingly important to the future of satellite connectivity. In the United States, the FCC proposed in September 2026 to make additional spectrum available for space-based wireless services, including applications involving homes, aircraft, ships, and satellite ground networks.
Challenges That Satellite Internet Still Faces
Despite rapid progress, satellite internet is not without limitations. The service can still depend on clear access to the sky, suitable equipment, sufficient satellite capacity, and favorable spectrum conditions. Urban environments can present additional challenges because buildings and other physical obstacles can interfere with satellite signals, particularly for direct-to-device services.
Cost is another consideration. While satellite broadband has become more competitive, users may still face equipment and service expenses that differ from conventional broadband. Network capacity can also vary according to location and demand. As adoption grows, operators will need to continually increase capacity to maintain service quality.
What the Future Could Look Like
The future of connectivity is likely to be hybrid rather than dominated by a single technology. Fiber will remain essential for high-capacity fixed networks. Cellular networks will continue serving populated areas. Wi-Fi will remain central to homes, offices, and public spaces. Satellites will increasingly fill geographic and resilience gaps between these systems.
For consumers, the most important change may be invisible. People may simply experience fewer dead zones and more reliable access to communication services. A smartphone could maintain basic connectivity during a remote journey, while businesses could automatically switch to satellite connectivity when their primary network fails.
Conclusion
Satellite internet has entered a new phase in which space-based connectivity is becoming part of mainstream telecommunications. LEO constellations are improving broadband performance, direct-to-device services are extending mobile coverage, and businesses are discovering new applications for connectivity in remote environments. At the same time, governments and regulators are adapting spectrum policies to accommodate the growing interaction between terrestrial and satellite networks.
The most important development is not that satellites will replace existing internet infrastructure. Instead, satellite networks are becoming another layer of the global connectivity system. They can extend coverage, provide resilience, support mobile users, connect remote businesses, and create new possibilities for IoT and digital services. With investment continuing across consumer, enterprise, government, aviation, maritime, and mobile markets, the satellite internet ecosystem is likely to become increasingly important.
.jpg&description=Explore how satellite internet is transforming global connectivity through LEO networks, direct-to-device services, rural broadband, enterprise use, and emerging 2026 trends.)